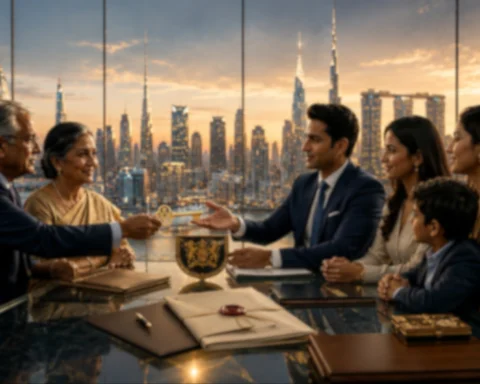
A family can have hundreds of crores in assets and still struggle to answer a deceptively simple question: who sees the entire financial picture?
One adviser handles the investment portfolio. A tax professional manages returns. Lawyers oversee trusts. A private bank provides credit. Another specialist sources Private Equity or Venture Capital deals. The family may also own real estate, operating businesses and gold investments.
That fragmentation creates a problem ordinary wealth management doesn’t always solve: coordination.
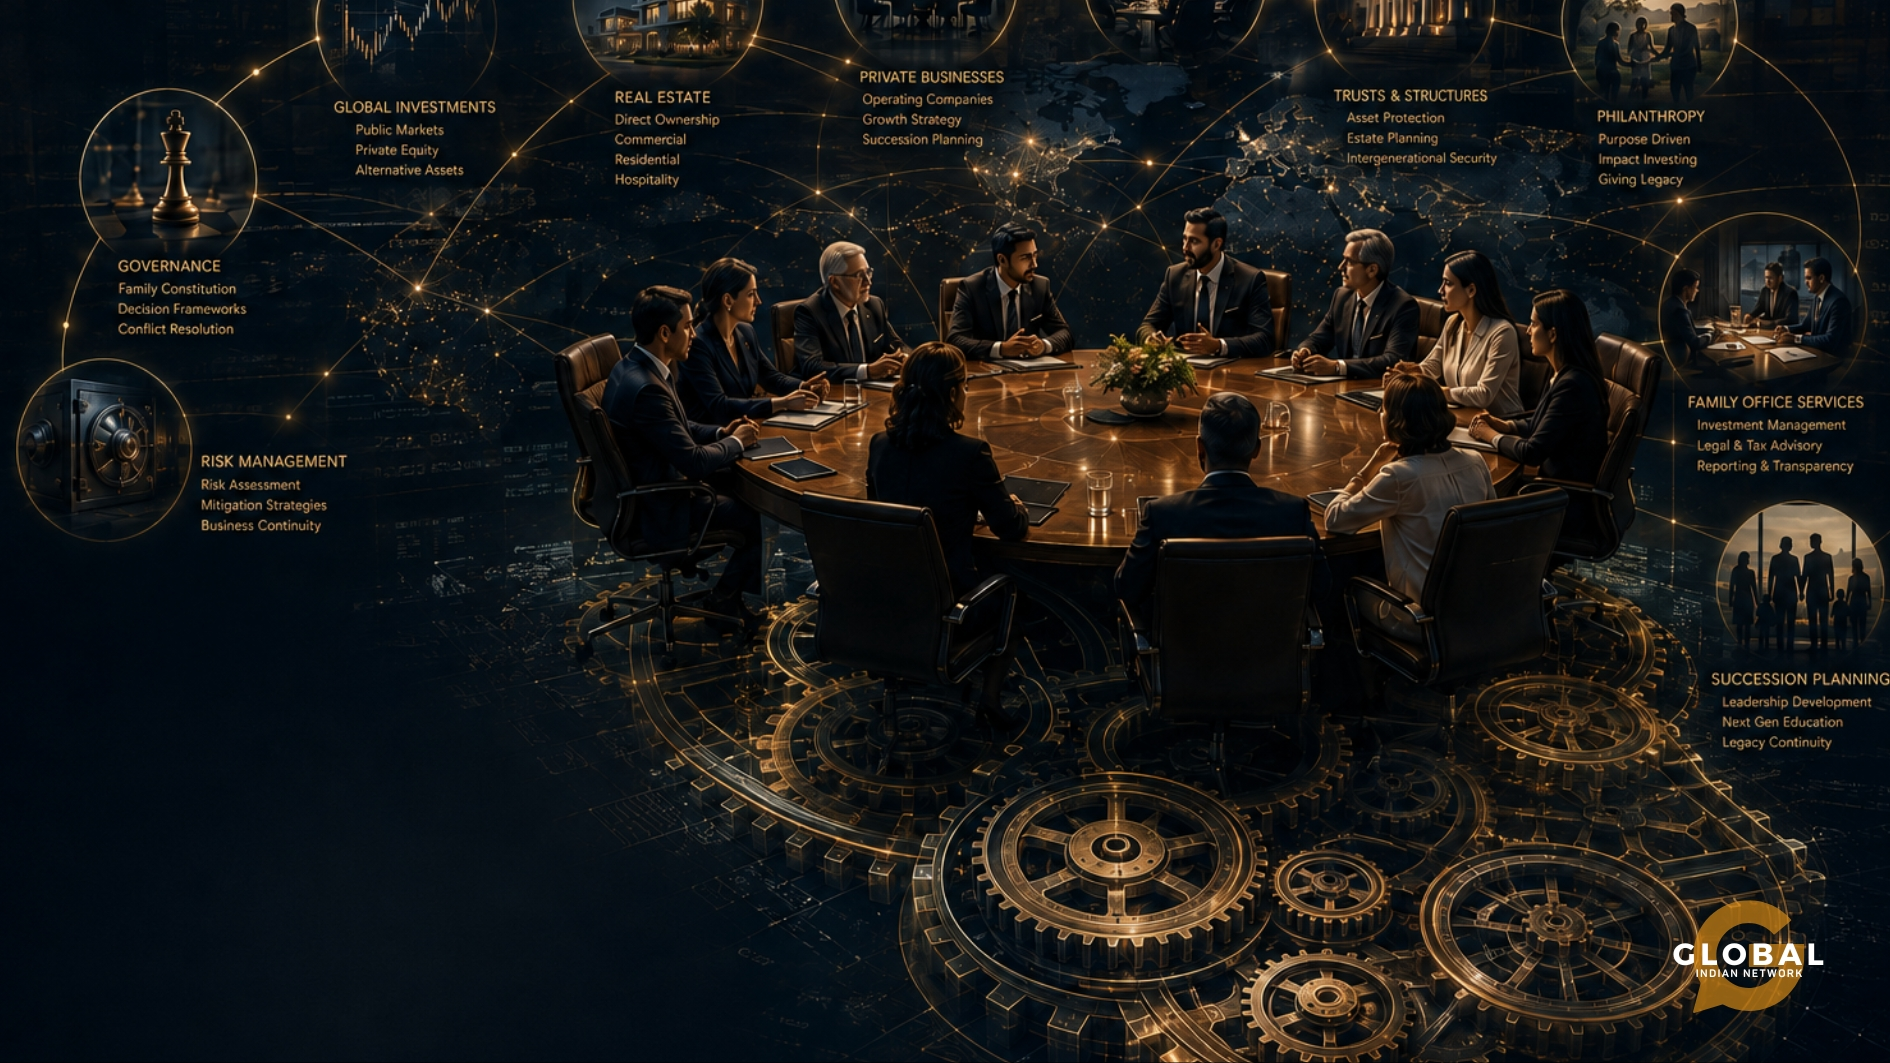
A multi-family office brings investment management, tax planning, estate planning, family governance and administrative support into a coordinated framework for several wealthy families. The model is becoming increasingly relevant in India as first-generation entrepreneurs turn business wealth into intergenerational wealth.
Table of Contents
What Is a Multi-Family Office?
A multi-family office is a professional organization serving multiple families with substantial net worth and complex financial affairs. Instead of building a dedicated team for one household, clients share investment professionals, technology, research, reporting infrastructure and specialist expertise.
The distinction from a conventional wealth manager matters. A wealth manager may primarily oversee an investment portfolio. A multi-family office can coordinate the wider financial ecosystem: asset allocation, investment advisory, risk management, tax services, estate and succession strategies, philanthropy structuring and consolidated reporting.
Not every provider offers every service. Some focus on investment management; others provide broader Multi Family Office Services.
How Does It Actually Work?
A strong family office starts with objectives rather than products. It examines the family structure, business interests, liabilities, liquidity requirements, asset levels and succession plan.
An initial self-assessment questionnaire may identify risk tolerance, governance arrangements and long-term priorities. The investment team can then build an investment planning framework covering asset allocation, portfolio management and investment implementation.
This holistic framework matters because a family’s balance sheet is rarely a collection of unrelated accounts.
A founder who owns 40% of a private company already has significant equity concentration. Adding an aggressive public-equity portfolio without considering that exposure may increase rather than reduce risk.
Core Services
Investment Management and Asset Allocation
Investment professionals may evaluate listed securities, fixed income, Private Equity, Venture Capital, real estate, gold investments and other private investments.
The objective isn’t necessarily to maximize returns every year. It is to align the investment portfolio with liquidity needs, time horizons, risk management and succession objectives.
Tax and Estate Planning
Tax planning becomes more complicated when families own assets through multi-layer entities, trusts or a foreign company.
A family office may coordinate tax return preparation, tax services, trusts and estates advice, family settlement arrangements and estate planning. External lawyers and tax specialists may still do the technical work; the family office helps ensure everyone works from the same plan.
Family Governance
Wealth often becomes more complicated when more people have a claim on it. Family governance can establish who participates in investment decisions, how family businesses are governed and what happens when a shareholder wants liquidity.
A family constitution can formalize principles around ownership, employment, distributions and dispute resolution. That can make a succession plan less dependent on informal conversations.
Consolidated Reporting and Technology
Consolidated reporting gives families a single view of assets held across banks, custodians, funds, private companies and other structures.
Modern client portals, digital tools, accounting software and wealth management platforms can provide real-time visibility into holdings and cash flows. Technology integration becomes especially valuable when accounts span jurisdictions.
But technology enables strategy; it doesn’t define it. A sophisticated dashboard cannot compensate for poor investment decisions or unclear governance.
Multi-Family Office vs Single-Family Office
A Single-Family Office is dedicated to one family. It can employ its own chief investment officer, investment teams, accountants and administrative staff, giving the family substantial control over investment decisions and service design.
A multi-family office spreads those costs across several clients. That can make access to specialist investment professionals more economical.
J.P. Morgan describes the choice as a trade-off involving control, customization, cost and shared resources. A single-family office may make more sense at higher asset levels or where a family’s affairs require highly customized infrastructure. A shared family office can be attractive when complexity is high, but an independent internal organization would be inefficient.
There is also an Outsourced Hybrid/Virtual Family Office model, where a family keeps some internal capabilities while outsourcing selected functions such as investment advisory, accounting or reporting.
Real-World Examples
Cresset, a U.S.-based family wealth firm, illustrates how the modern shared family office model has expanded beyond portfolio management. Its offering includes investment advisory, tax strategy, estate planning, private investments, trust services, family governance and philanthropy.
India has developed its own examples. Equirus-Credence FO provides family-office and wealth-management solutions, while Ashutosh Finserv markets multi-family office services spanning wealth management, investment oversight, governance and legacy planning.
These examples matter because they show the direction of the industry: family-office providers increasingly combine investment planning with the non-investment decisions that determine whether wealth remains durable across generations.
What Does It Cost?
Pricing varies. A provider may charge asset-based fees, administrative fees, retainers or, in some structures, a performance-based fee. Families should therefore look beyond the headline percentage.
For example, a 0.75% asset-based fee on $23.4 million equals $175,000 a year before underlying fund expenses, transaction costs, custody charges or external legal and tax services. The better question is what the family receives for that cost.
A lower-cost wealth manager may be sufficient for straightforward investable assets. A family-office structure becomes easier to justify when the family actually uses its reporting, governance, private-market access, tax coordination and succession capabilities.
Risks and Limitations
A multi-family office isn’t automatically independent. Families should understand whether advisers receive commissions, distribution payments or other incentives connected to recommended products.
Conflicts can also arise when a firm has preferred investment managers or proprietary offerings.
Confidentiality is another concern. Family offices handle information about net worth, business interests, bank accounts, trusts, philanthropy and lifestyle services. Strong cybersecurity, access controls and client portals are therefore essential.
When Should a Family Consider One?
Net worth is only one variable. A family may consider a multi-family office when its affairs involve several generations, multiple businesses, complex ownership structures, international assets, substantial private investments or an approaching liquidity event.
The trigger is often complexity rather than wealth alone. A shared family office becomes more useful when coordination itself starts consuming significant time.
If a family has $5.85 million in straightforward financial assets and wants conventional portfolio management, a wealth manager may be sufficient. If it has $17.5 million spread across businesses, trusts, real estate, private investments and international accounts, coordination can become much more valuable.
The Future of Family Offices
The next generation of family offices will combine human judgment with increasingly sophisticated digital tools.
AI-assisted reporting, automated reconciliation and real-time portfolio visibility can reduce administrative work. Multi-family offices will increasingly be expected to combine these tools with human judgment.
Younger family members are likely to expect stronger client experience, digital access and clearer explanations of how family wealth is managed.
Investment teams will also navigate a broader opportunity set, from Venture Capital and private markets to sustainable business and global financial ecosystems.
Yet technology can’t resolve a family disagreement over control, nor can an algorithm decide how parents should transfer ownership to their children. Family governance, succession planning and trusted advice will remain central.
How to Choose the Right Provider
Before selecting a multi-family office, families should ask:
- What services are genuinely included?
- How are asset-based fees and performance-based fee arrangements structured?
- Are investment recommendations independent?
- Which functions are handled internally and which are outsourced?
- Who controls investment implementation?
- How are private investments evaluated?
- How does the firm handle tax planning and estate planning?
- Can it coordinate offshore advisory and Cross-border investments?
- What technology provides consolidated reporting?
- Who will actually be responsible for the family relationship?
The last question is easy to overlook. A family isn’t hiring a logo. It is trusting people with its family wealth.
The Bottom Line
A multi-family office is best understood not as another investment product, but as an operating system for complex family wealth.
Most importantly, a shared family office’s strongest contribution is coordination: connecting investment management with tax planning, estate planning, succession planning, family governance and consolidated reporting.
For some wealthy families, a Private Bank or wealth manager will remain the better choice. For others, the scale and complexity of their affairs will justify a Single-Family Office. Between those models, a multi-family office can offer institutional capabilities without requiring one family to build every function from scratch.
The real test is whether the structure helps a family make better decisions, reduce avoidable risks and transfer wealth with greater clarity.
If it does, the value of a shared family office lies far beyond portfolio returns. It lies in making family wealth easier to govern, preserve and pass forward.
FAQs
Do Ambanis have a family office?
The Ambani family manages its own single-family office, known as the Ambani Family Office.
Does Elon Musk have a family office?
Elon Musk operates a family office known as Excession LLC, founded in 2016.